Sampath Bank PLC (SAMP) Initiation Report - BRS Equity Research
Initiation Reports
03/11/2026
153
0
Strong Loan Momentum, Buffers Built: Earnings Growth Resumes in 2027E
📈 Strong 2Q Earnings
PATMI rose 65% YoY to LKR 11.0bn (EPS: LKR 9.41), supported by 18% YoY NII growth to LKR 24.6bn and 23% growth in net fees. Impairment charges fell 65% YoY after provisions were front-loaded in 1Q.
💳 Resilient Credit Demand
Gross loans grew 19% YTD to LKR 1.54tn. We expect 26.5% credit growth in 2026E, moderating to 12–13% in 2027–28E, with NIM widening towards ~4.4% as rate cuts ease funding costs from 2027E.
🛡️ Buffers Built Ahead of the Cycle
Gross Stage 3 ratio improved to 6.54%, well below the sector’s 9.1%, with coverage at 65.6% and a CET1 ratio of 13.4%.
📊 Earnings Growth Resumes
We forecast PATMI of LKR 40.3bn in 2027E (+17%) and LKR 47.8bn in 2028E (+19%), a 14% CAGR over 2025–2028E.
🎯 Valuation & Recommendation:
SAMP.N TP (2027E): LKR 191.00 (+35.9%) | BUY
⚠️ Risks: (1) Prolonged Middle East conflict (2) Rising credit costs (3) Weaker loan growth (4) NIM compression
Discussion (0)
Latest Reports
Free
Banking_Sector_Update_Fitch_Upgrade_Nov_2026_-_BRS_Equity_Research
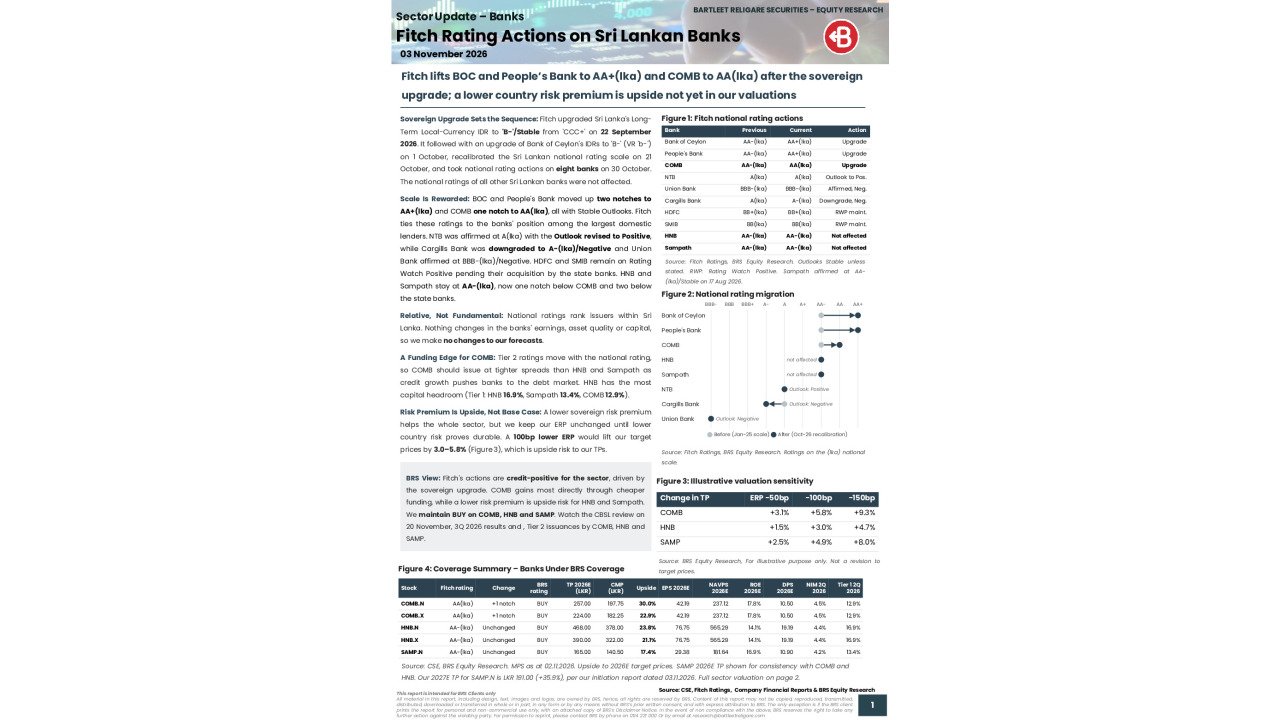
Fitch Upgrades Follow the Sovereign: Credit-Positive for Banks, ...
78
0
Related Reports
Free

Commercial Credit and Finance PLC (COCR) ...
🛵 Wheels in Motion: Yield-Driven Growth & ROE ...
859
0
Free
TOKYO CEMENT COMPANY (LANKA) PLC - ...
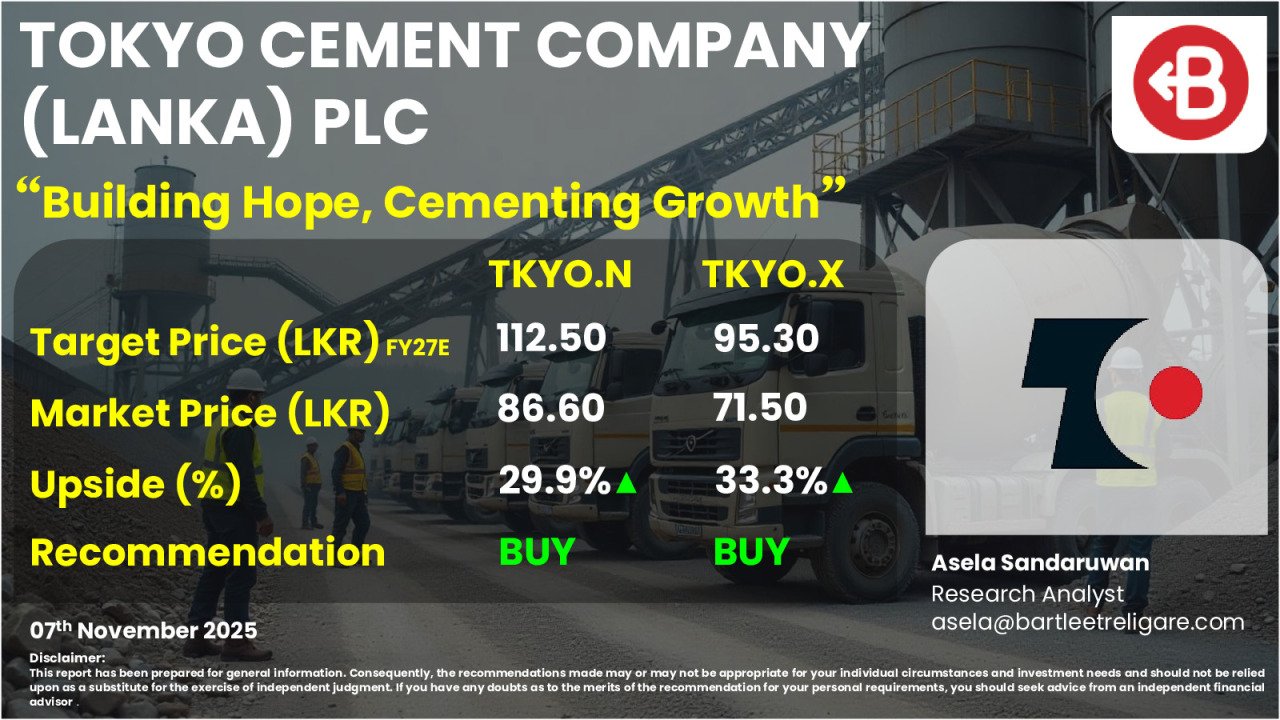
Tokyo Cement Company (Lanka) PLC (TKYO), Sri Lanka’s ...
1.5k
0
Subscription

Free
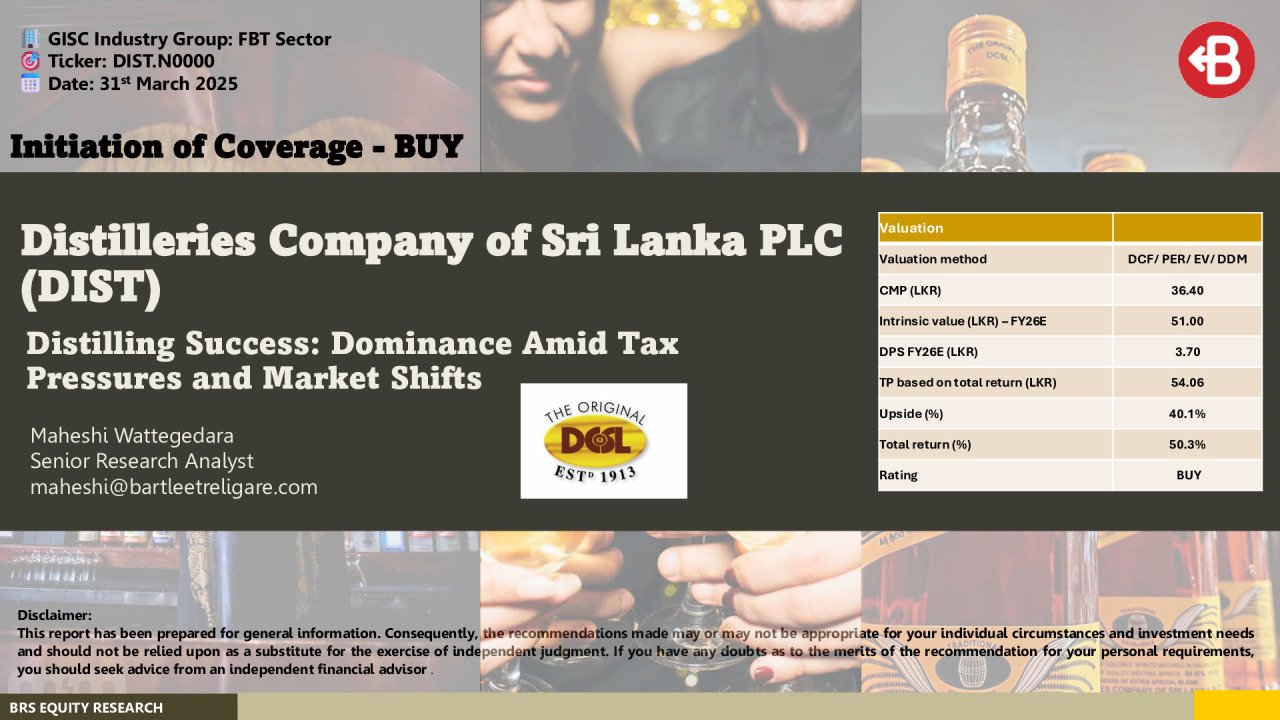
Distilleries Company of Sri Lanka PLC ...
We initiate coverage on Distilleries Company of Sri ...
1.2k
0
You must login to post a comment.