SFIN Equity Update - Attractive on Rights, Stretched on CMP - BRS Equity Research
Loading...
Initiation Reports
27/08/2025
428
0
Recommendation:
✅ Existing Shareholders: Subscribe to Rights ⚠️ New Investors: Growth Largely Priced-In
FY27E TP: LKR 61.00 (~9% downside from CMP)
📌 Rights Issue Strategy
Existing Shareholders – Subscribe ✍️ - Rights priced at LKR 26.50, ~130% upside.
Trade Rights Smartly 💰:
Rights Intrinsic value LKR 34.50;
sell above LKR 34.50, buy below LKR 30.00.
🔹 Aggressive Lending Growth Backed by Rights Funds
Rights issue raising LKR 2bn strengthens capital adequacy to sustain MSME-focused lending.
🏢 Branch Expansion to Target Underpenetrated MSMEs
4 new branches added in FY25; 10 more planned in FY26 for semi-urban, high-yield segments.
🛡️ Strong Asset Quality
Prudent provisioning maintains robust asset quality despite rapid growth.
💸 Valuations
Trades at forward PER 12.3x and PBV 2.0x. Forecasted ROE 20% remains attractive but largely priced in.
⚠️ Investment Risks
MSME sector exposure, rapid RWA growth, inflation-driven tightening, slower credit demand, competition from banks/NBFIs.
Discussion (0)
Latest Reports
Related Reports
Free
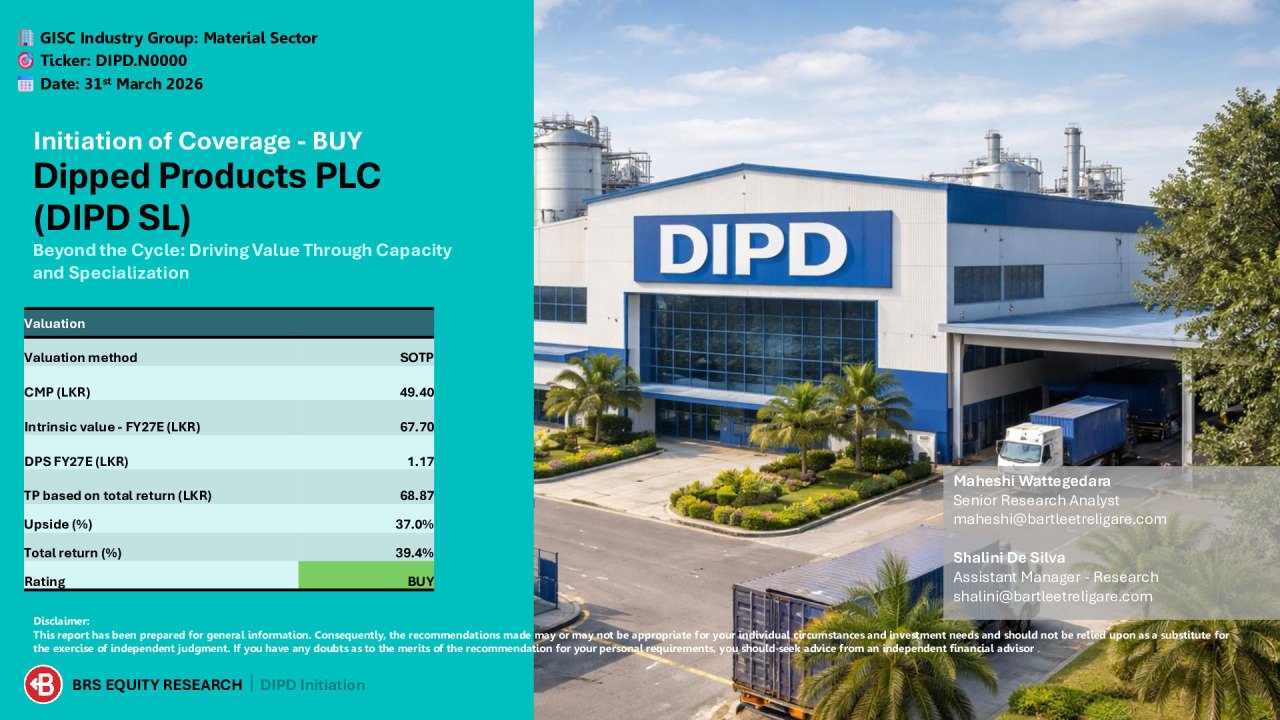
Dipped Products PLC (DIPD) - Initiation ...
Beyond the Cycle: Driving Value Through Capacity and ...
953
0
Free
Free
You must login to post a comment.