TJL Earnings Review 2Q FY26 - BRS Research
Loading...
Earnings Reviews
03/12/2025
357
0
📉TJL Earnings Review 2Q FY26 – Tariff-Driven Demand Weakness Pushes TJL into Earnings Freefall
• PAT down 80% YoY to LKR 149.9mn as revenue fell 10% YoY; volumes dropped 5–6% with added pressure from ASPs & product mix.
• 📉 Margins deteriorated (GP 8.0%, EBIT 1.9%) due to sustained pricing pressure and weak demand.
• 🇺🇸⚠ U.S. reciprocal tariffs spike on India (to 50%) severely disrupted TJL’s largest production base, worsening near-term performance.
• 🔻 ASPs expected to decline further amid easing raw-material costs and competitive tariff-driven pricing.
• 🔮 Demand weakness likely to persist medium–long term, with cost savings and LKR depreciation offering only limited relief.
• ❗ Rating downgraded to SELL with a TP of LKR 31.10, reflecting a prolonged subdued demand outlook unless U.S. tariffs ease.
Discussion (0)
Latest Reports
Related Reports
Subscription
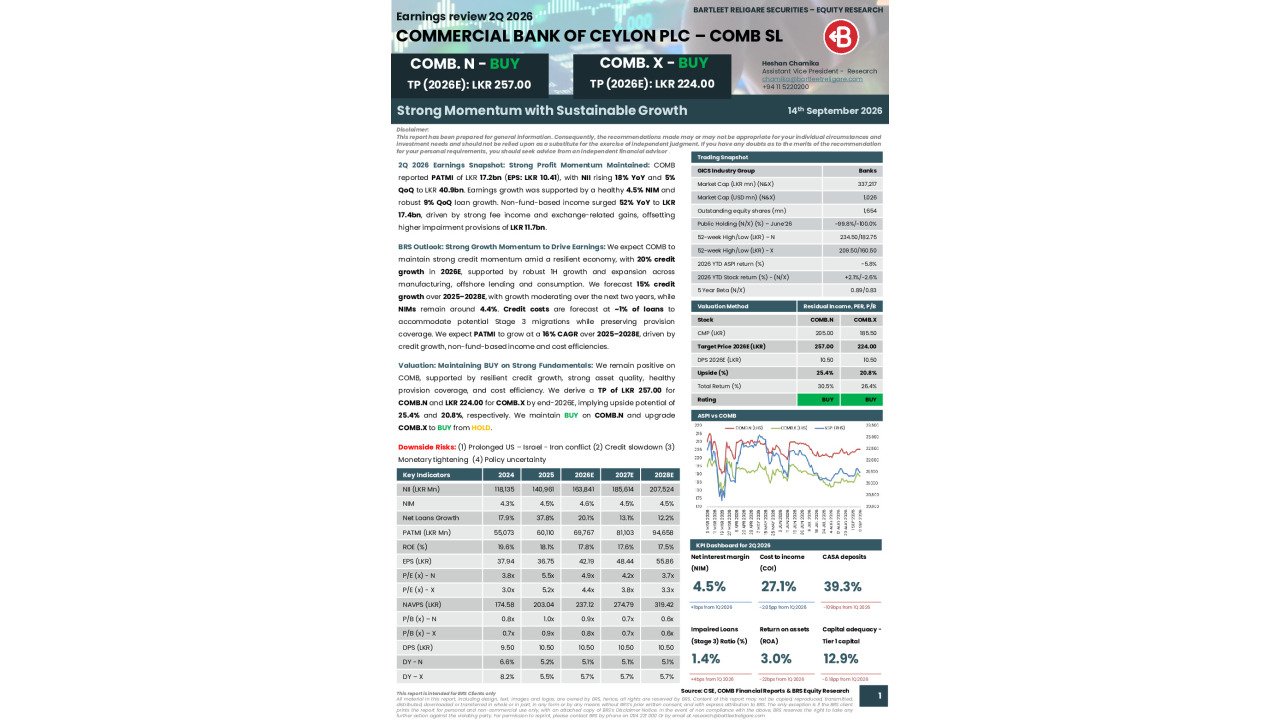
COMB 2Q 2026 Earnings Review - ...
Strong Momentum with Sustainable Growth 📈 Strong Earnings ...
92
0
Subscription
You must login to post a comment.